Taking a loan is a major economic decision. Whether you are planning to buy a home, purchase a vehicle, pay for education, manage a business expense, or cover a personal requirement, choosing the right loan can affect your monthly budget for several years.
Many borrowers compare loans by looking only at the interest rate. While the interest rate is important, it is not the only factor that determines the actual cost of borrowing. Loan comparison should also include the loan amount, repayment tenure, EMI, processing fees, eligibility requirements, and other applicable charges.
Using a loan calculator can make this process easier by helping you estimate your monthly EMI and understand the potential repayment cost. At the same time, checking loan eligibility can help you identify options that match your financial profile.
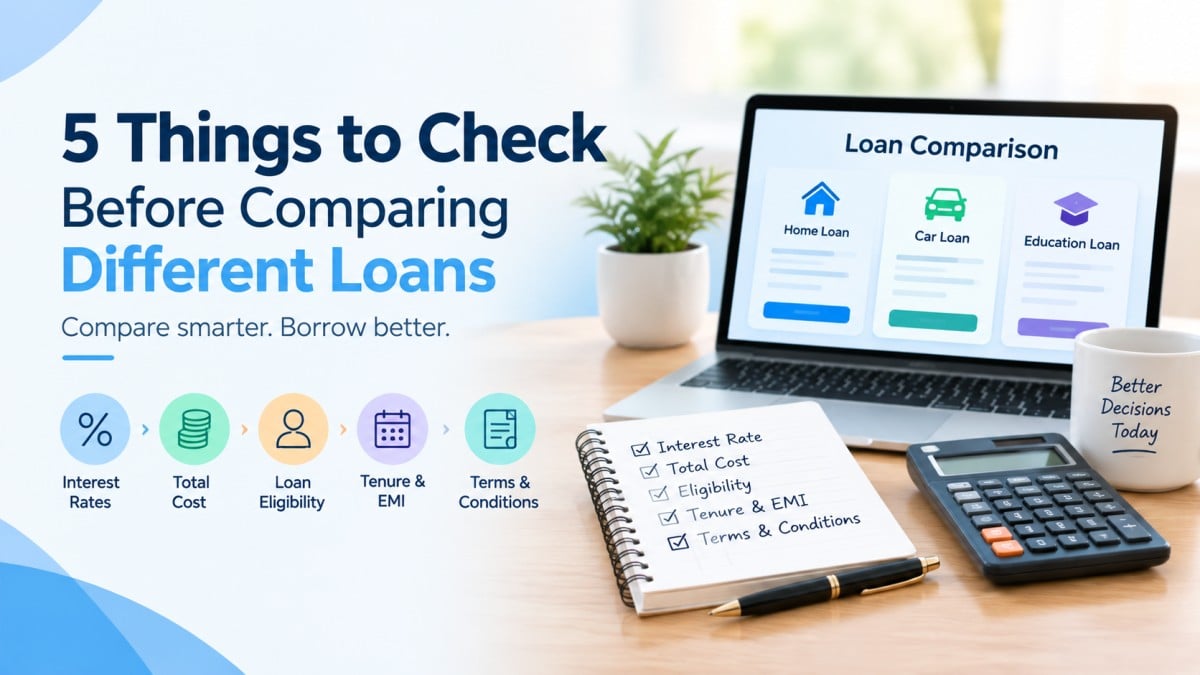
Here are five important things to check before starting a comparison for loan options.
1. Compare the Interest Rates
The interest rate is one of the first things borrowers usually check when comparing loans. It determines how much interest you may pay in addition to the principal amount borrowed.
However, simply choosing the loan with the lowest advertised rate may not always provide a complete picture. Interest rates can vary depending on factors such as the type of loan, borrower profile, credit history, income, loan amount, and repayment period.
When conducting a loan comparison, check whether the quoted rate is:
- Fixed or variable
- Applicable for the entire tenure or only an initial period
- Based on your individual eligibility
- Associated with any specific conditions
- Calculated using the reducing-balance or another applicable method
Comparing the actual applicable rate rather than relying only on promotional figures can give you a clearer understanding of the borrowing cost.
2. Check the Total Cost of the Loan
The interest rate is only one part of the overall cost. A loan may also include processing fees, documentation charges, administrative fees, late-payment charges, prepayment or foreclosure charges, and other applicable costs.
For this reason, borrowers should compare the total cost of the loan rather than focusing exclusively on the EMI or interest rate.
For example, two loans could have similar interest rates but different processing fees and other charges. Looking at the complete repayment structure can help you understand which offer fits your budget.
A loan calculator can help estimate EMI and total interest based on the loan amount, interest rate, and tenure. You can then consider additional charges separately to create a more complete comparison.
3. Check Your Loan Eligibility
Before comparing multiple loan offers, understand whether you are likely to qualify for them. This is where loan eligibility becomes important.
Lenders may consider several factors when assessing an application, including:
- Age
- Income
- Employment or business profile
- Credit history
- Existing financial obligations
- Loan amount requested
- Repayment capacity
- Relationship with the lender, where applicable
Eligibility requirements can differ between loan products and lenders. Meeting the basic criteria does not necessarily guarantee approval because the final decision depends on the lender’s assessment. Checking your eligibility before applying can help you focus your loan comparison on realistic options.
It can also help you avoid making multiple applications without first understanding whether the loan requirements match your financial situation.
4. Compare the Loan Tenure and EMI
The repayment tenure determines how long you will take to repay the loan. It can also have a significant effect on your monthly EMI and total interest cost.
Generally, a longer tenure can reduce the monthly EMI but may increase the total interest paid over the life of the loan. A shorter tenure can increase the monthly repayment while potentially reducing the overall interest cost.
This is why borrowers should not compare loans based on EMI alone.
Use a loan calculator to test different combinations of:
- Loan amount
- Interest rate
- Repayment tenure
- Monthly EMI
- Total interest payable
For example, if a longer tenure makes the EMI more comfortable, you can compare that option with a shorter tenure to understand the difference in total repayment.
The right balance depends on your income, monthly expenses, financial goals, and repayment capacity.
5. Read the Terms and Conditions Carefully
Before selecting a loan, read the important terms and conditions instead of relying only on the headline interest rate. Pay attention to details such as:
- Processing fees
- Prepayment conditions
- Foreclosure charges
- Late-payment charges
- EMI payment dates
- Interest-rate changes
- Additional service charges
- Required documents
- Security or collateral requirements, where applicable
These terms can affect the actual cost and flexibility of the loan.
For example, a borrower who expects to repay a loan early should understand the applicable prepayment or foreclosure conditions before choosing a particular option.
A detailed comparison for loan offers should therefore include both financial costs and the practical terms attached to each loan.
How a Loan Calculator Helps With Loan Comparison
A loan calculator is a useful tool when comparing different borrowing scenarios. Instead of calculating EMI manually for every option, you can enter different loan amounts, interest rates, and repayment tenures to see how the numbers change.
For example, suppose you are comparing two hypothetical loan options. You can calculate the EMI for each option and then compare the estimated total interest payable.
This can help you understand the difference between:
Lower EMI + longer tenure
and
Higher EMI + shorter tenure
The calculator does not decide which option is suitable for you. Instead, it gives you numbers that can help you evaluate the options based on your financial circumstances.
Why Loan Eligibility Should Be Checked Early
Loan comparison becomes more useful when you first understand your borrowing capacity.
For example, if you are looking for a larger loan but your income and existing obligations limit the amount you may qualify for, comparing offers based on an unrealistic loan amount may not be useful.
An eligibility check can provide an initial understanding of factors that may influence your potential borrowing amount. However, eligibility calculators and preliminary estimates should not be treated as a guarantee of approval.
The final loan amount, interest rate, and approval decision are determined by the respective lender after evaluating the application.
Don’t Compare Loans Based on EMI Alone
A common mistake during loan comparison is choosing the option with the lowest monthly EMI.
A lower EMI may result from a longer repayment period. While this can make monthly payments easier to manage, it may also mean paying interest for a longer period.
Consider three factors together:
Monthly EMI: Can you comfortably afford the payment?
Total interest: How much interest could you pay during the repayment period?
Overall loan cost: What will the loan cost after considering applicable fees?
Looking at all three gives you a more complete picture than comparing EMI alone.
Create a Simple Loan Comparison Checklist
Before making a decision, you can create a simple checklist for each loan option. Check the:
- Interest rate
- Loan amount
- Loan tenure
- Estimated EMI
- Total interest
- Processing fees
- Other applicable charges
- Prepayment and foreclosure terms
- Eligibility requirements
- Documentation requirements
- Collateral or security requirements, if applicable
This approach makes it easier to compare different loan offers using the same criteria.
Final Thoughts
A proper loan comparison involves more than finding the lowest interest rate. Borrowers should consider the total borrowing cost, loan eligibility, repayment tenure, EMI, fees, and terms and conditions before making a decision.
Using a loan calculator can make the numerical part of the comparison easier, while checking eligibility can help you focus on loan options that are relevant to your financial profile.
Whether you are comparing a personal loan, home loan, car loan, education loan, or business loan, taking time to understand the complete offer can help you make a more informed borrowing decision.
Before applying, compare the available options carefully, read the lender’s current terms, and make sure the expected repayment fits comfortably within your budget.